By Ronnie Mbuqe
Expected spending often leaves out small repeats, irregular bills and the timing of deductions. The total can disagree with your mental picture even when every transaction is valid.
Group actual payments over a defined period and compare them with the plan. Work from records rather than guessing which one purchase must be to blame.
RM
Ronnie Mbuqe
Author · ExplainItSimply
24 July 2026
18 minute read
English
Look closerLook beneath where everyday money goes
Money often feels as though it disappeared because spending happened in many small moments. The answer is not shame. It is making the invisible pattern visible.
The story beginsPayday arrives once, but spending arrives every day
A salary enters the account and creates a brief feeling of relief. Rent or housing costs leave. Transport, electricity, groceries, school needs, data, subscriptions and debt payments follow. Then small purchases continue through the month. By the time the balance becomes uncomfortable, it can feel as if the money simply disappeared.
Money did not disappear. It followed a pattern that was difficult to see while it was happening. A budget is not punishment and it is not proof that someone earns enough. It is a picture of the real situation, allowing choices to be made before urgency makes them instead.
£
The simplest answer
Money feels as if it disappears because income often arrives in a few large amounts while spending leaves through many large and small payments over time.
Why can a month feel cheap one purchase at a time but expensive in total?
Memory tends to highlight unusual purchases, while routine costs spread across the month.
Trace the explanation
A transaction record makes the pattern inspectable. Group spending and compare a consistent period before choosing what to change.
Source and further reading: Consumer Financial Protection Bureau
Simply explainedThe four groups competing for the same income
Essential needs come first: housing, food, transport, utilities, medicine and family responsibilities. Financial commitments follow, including debt, insurance or contracts. Flexible wants include convenience food, entertainment and impulse purchases. Future needs include savings and emergency money.
The difficulty is that all four groups use the same limited income. When future needs are always left until the end, there may be nothing remaining. Planning means assigning money a job while the full amount is still visible.
⌂
Fixed essentials
These are costs that are difficult to avoid in the short term. They should be listed first because pretending they do not exist makes the rest of the budget unrealistic.
A closer lookA balance can include someone else's next payment
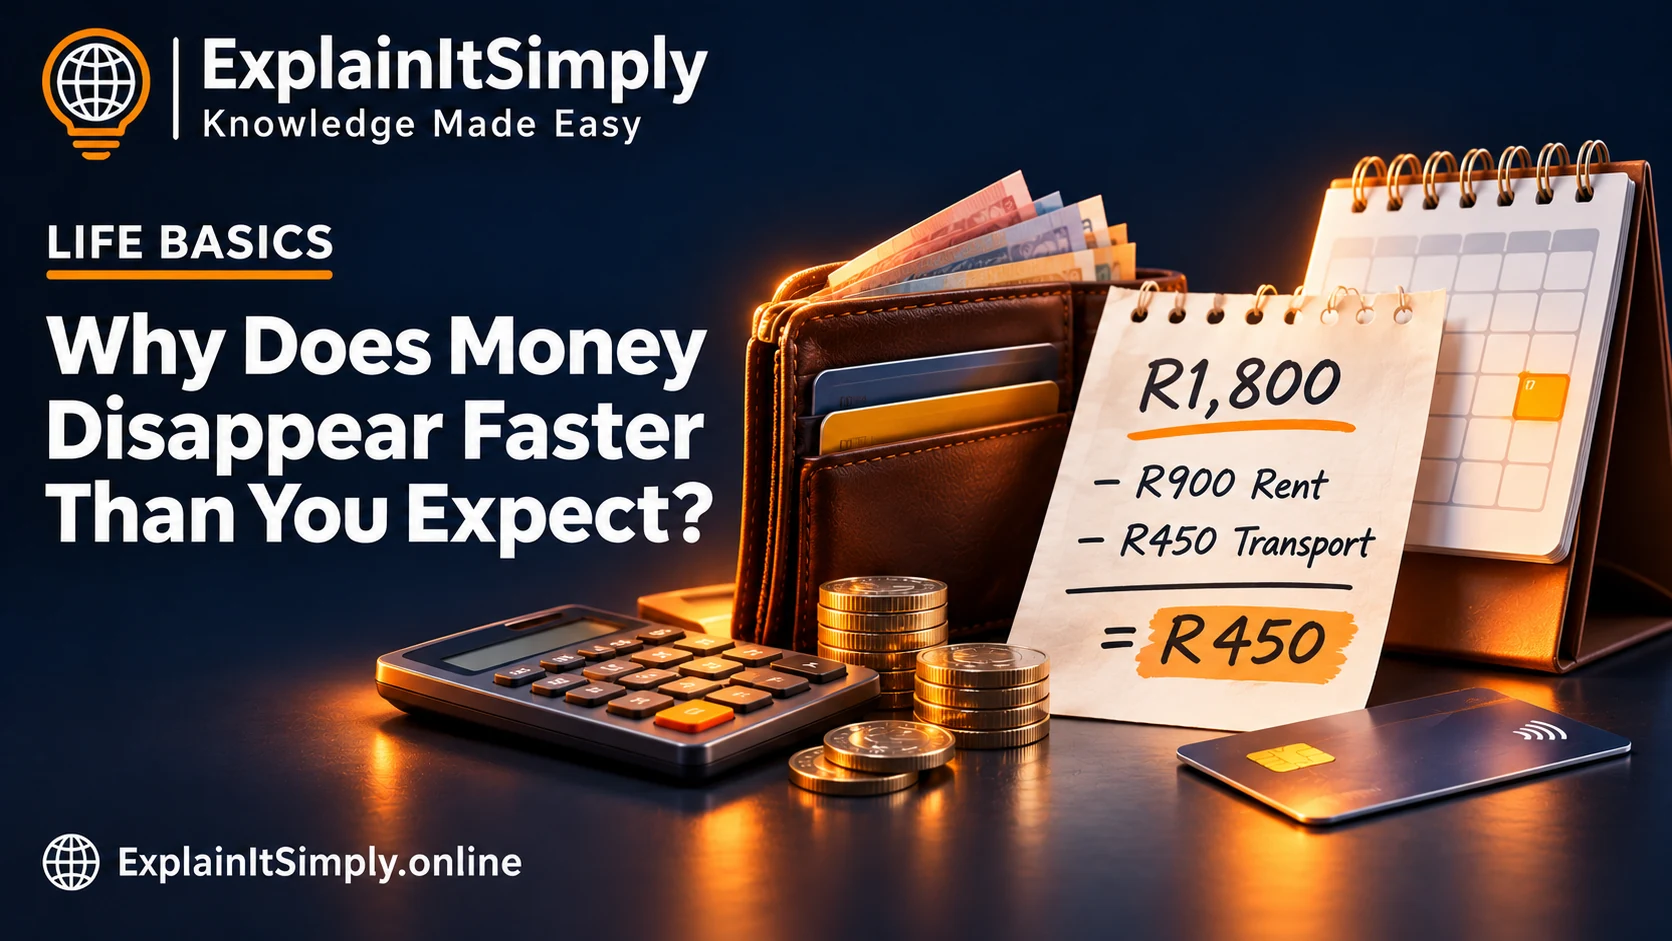
A balance shows R1,800, but R900 rent and R450 transport are still due before payday. That leaves R450 before food and anything unexpected.
Work through the distinction
Start with the balance, subtract obligations that have not cleared and then consider the days remaining. A pending card transaction can make the displayed balance an incomplete picture. Verify the bank's definition of available balance rather than assuming it.
What remains after the two stated obligations?
Choose an answer to see feedback. You can try again.
Show the answer and explanation
R450. Start with the balance, subtract obligations that have not cleared and then consider the days remaining. A pending card transaction can make the displayed balance an incomplete picture. Verify the bank's definition of available balance rather than assuming it.
🛒
Variable essentials
Food, electricity and transport are necessary, but the amount can change. Tracking them helps reveal where practical adjustments are possible.
★
Wants and convenience
A single purchase may be affordable, while the repeated habit becomes expensive. The issue is the total pattern instead of one cup of coffee.
➜
Future money
Savings, emergency funds and debt reduction protect future choices. They usually need to be planned instead of left to chance.
Follow one salary through the month
This simple story shows why the final balance can surprise someone who never saw the complete flow.
Income arrives
The full balance looks large because none of the month's responsibilities have left yet. This is the best moment to plan.
Fixed commitments leave
Housing, contracts, insurance and debt orders reduce the amount. These costs often happen automatically, so they can be forgotten when looking only at daily spending.
Daily needs continue
Food, transport, electricity and family costs use the remaining balance in smaller pieces.
Small convenience spending adds up
Delivery fees, snacks, subscriptions and quick purchases do not feel serious individually. Together they may consume the amount that was meant for saving.
An unexpected cost appears
A repair, medical need or family emergency creates pressure. Without emergency savings, credit may become the quickest solution.
The month ends
The person remembers only a few big purchases and asks where the money went. Reviewing the categories reveals the complete answer.
Why do small purchases seem to arrive with friends?
A £3 purchase feels harmless because the brain compares it with the current balance, not with every other £3 purchase made throughout the month. Convenience also removes friction: tap, approve and continue. The emotional moment of handing over cash is weaker.
The funny side is that small purchases behave like guests who each say, ‘I will not eat much.' By the end of the evening, the fridge is empty. The lesson is not that every small enjoyment is wrong. The lesson is that repeated spending needs a planned space.
Where this appears in real lifePractical changes that reveal the real picture
The best money advice adds visibility and choice instead of shame.
▤
Use realistic categories
List what you truly spend, including family support and irregular costs. A dishonest budget cannot guide real life.
⌕
Review subscriptions
Small automatic payments can continue long after they stopped providing value. Review them regularly.
⚖
Separate needs from urgency
A loud request is not always the most important need. Pause before allowing the moment to choose for the whole month.
☂
Build a small emergency buffer
Even a modest amount can reduce the need to borrow when an unexpected cost arrives.
Why is money left in the account not always money free to spend?
A current balance may still need to cover payments due before the next income. Pending and scheduled obligations change what is available for new choices.
Take a fictional R1,000 balance with R800 of unavoidable payments still due. Only R200 remains before other needs; the displayed balance alone did not show that commitment.
Five small automatic payments can become one large invisible commitment
A hypothetical R49 subscription looks modest alone. Five such subscriptions total R245 per month, or R2,940 over twelve months if the prices stay the same. Multiplying recurring amounts makes a pattern visible that separate notifications can hide.
Review actual statements and mark repeating charges before assuming the cause is careless cash spending. Some costs are essential and some can be changed. Cancel through the provider's proper process and check the next statement rather than assuming deleting an app ended the agreement.
Small recurring charges to An annual total you can compare
Is money left in the account fully available if debit orders are still due?
No. Some of the balance may already be committed. Compare available cash with upcoming obligations, not only the number displayed today.
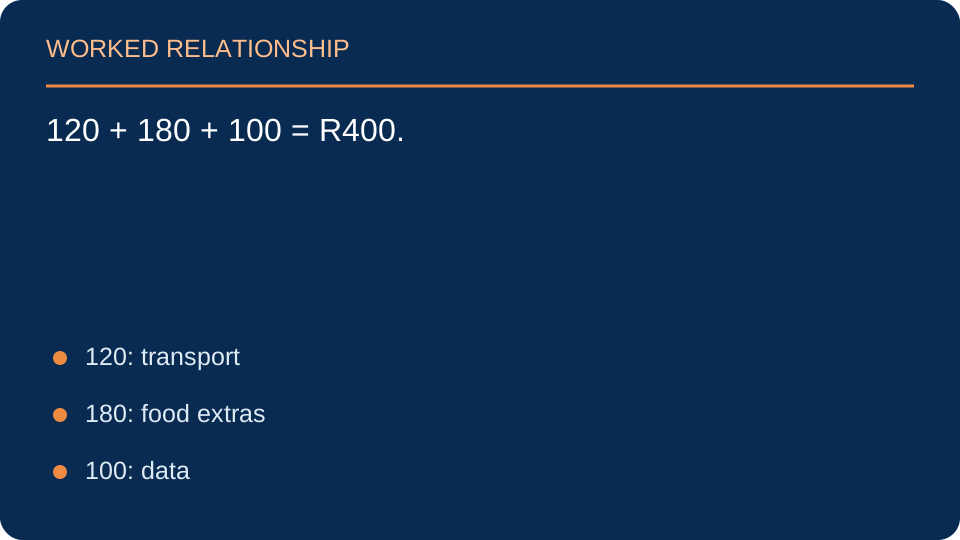
A fictional week includes R120 transport, R180 food extras and R100 data. What is the combined spend?
Trace the explanation
120 + 180 + 100 = R400. The labels and amounts are invented. Use actual records when making a personal budget, and keep necessary costs distinct from optional choices.
Source and further reading: Consumer Financial Protection Bureau
Patterns that empty the account
Four ways money quietly leaves before you notice
Most people do not lose money through one dramatic decision. It leaves through repeated, almost invisible patterns. Recognising the pattern is the first useful step.
↻
The “only once” purchase that repeats
A snack, a small delivery fee or a convenient top-up can feel too small to track. When the same choice happens several times a week, the total becomes a real budget line that never appeared on paper.
📅
Commitments that arrived before the salary
Subscriptions, loan instalments, family support and school costs often claim money the moment it arrives. By the time you look at what is left, the free portion is already smaller than it felt on payday.
⏳
Paying for speed instead of planning
Late fees, emergency transport, last-minute data or convenience-priced food are often the price of running out of time or preparation. A little planning earlier in the week can protect a surprising amount of cash.
🤝
Help that has no boundary
Supporting family or friends is often important and necessary. Without a clear, realistic limit, requests can expand until they compete with rent, food or debt payments. A planned amount is kinder to everyone than repeated shortfalls.
A practical starting exercise
Map one month in one evening
You do not need perfect records. You need a clearer picture than the one in your head.
- Write the income for the month (salary, grants, side work, whatever actually arrives).
- List every fixed claim that leaves soon after payday: rent, transport, school fees, loan payments, agreed family support.
- Add the flexible but regular costs: food, data, electricity, small daily purchases.
- Circle the surprises from the last month (repairs, medical costs, unexpected requests).
- Name the leftover honestly. If the number is negative or tiny, the plan needs adjustment before the next payday arrives.
This single page becomes a decision tool. It does not judge you; it shows where the money is already spoken for and where small changes can still create room.
Question 1Which small costs repeat without being noticed?
Question 2How much money was committed before payday arrived?
Question 3What changes when every rand is given a job?
Detailed answers about where everyday money goes
Does budgeting work when income is low?
A budget cannot create money that does not exist, but it can show the size of the gap, protect essential priorities and support clearer decisions. When income is limited, the first useful result is honesty: which costs are fixed, which are flexible, and which commitments already claim the next payday.
Sometimes the honest conclusion is that additional income, reduced commitments or outside support is necessary. The budget does not solve poverty by itself; it makes the numbers visible so action can be planned.
Should I stop all enjoyment to save money?
No. A plan that removes every enjoyable item is often difficult to maintain and can fail suddenly. A more practical approach is to give reasonable enjoyment a clear, limited amount so it does not quietly consume money needed for essentials or debt.
When enjoyment has a deliberate place in the plan, it is less likely to appear as unexplained spending at the end of the month.
Why is credit expensive?
Credit allows you to use future income today. Interest and fees pay the lender for risk, administration and the time value of money. The convenience of buying now reduces the money available in future months, and the longer the balance remains, the more those costs accumulate.
That is why small repeated credit purchases can become expensive even when each purchase felt manageable on its own. See also how credit works in simple terms.
How much should I save?
The right amount depends on income, responsibilities and existing debt. A useful starting point is an amount that is realistic and repeatable every month, even if it is small. Consistency builds the habit and the emergency buffer; the amount can increase when income rises or costs fall.
If debt interest is high, reducing expensive debt may be a stronger first priority than saving large amounts, while still keeping a small emergency reserve where possible.
What is the first step when money is already out of control?
List income, essential costs, debts and due dates on one page. Contact creditors early where needed, stop adding avoidable new debt, and seek reputable financial guidance if the situation is serious or includes legal risk.
Clarity comes before optimisation. Once the full picture is visible, priorities become easier to rank and smaller improvements can be applied without guessing.
You cannot remember where the money went. What evidence would help more than guessing?
One reasoned response
Review transaction records and note cash purchases too. Look for repetition, automatic charges and category totals, then decide which changes would preserve what matters most.
Source and further reading: Consumer Financial Protection Bureau
Continue the storyContinue beyond where everyday money goes
Money basicsHow Money Works
Understand income, value, exchange and everyday financial choices.
Read guidePlanningBudgeting Basics
Create a practical budget that reflects real life.
Read guideChoicesSaving vs Spending
Understand the trade-off between present use and future security.
Read guideBorrowingWhat Is Credit?
Learn how credit works before using future income.
Read guide
Further reading
This article is educational and not personal financial advice. Money rules, rates and consumer protections can change, so check current information with South African authorities.
Sources
Sources and further reading