By Ronnie Mbuqe
The instalment describes one payment, not the full repayment. A longer term can reduce each payment while extending interest and other costs.
Compare the cash received, required payments, fees and total amount repayable using the actual agreement. A low monthly figure alone cannot establish affordability or value.
First, the basic idea
Credit is neither good nor bad by itself. It’s a financial tool, and like any tool, it can either help you build wealth or slowly trap you in debt.
Does being approved for credit mean the repayment fits your budget?
Borrowing moves spending into the present while creating future obligations.
Trace the explanation
The payment, fees, interest and duration determine the commitment. A lender's approval does not tell you which other household priorities you may have to give up.
Source and further reading: National Credit Regulator
Credit Lets You Use Future Income Today
Credit is an agreement where another party gives you purchasing power now and you promise to repay later. The lender accepts the risk that repayment may be late or may never arrive, so the agreement usually includes interest, fees, security or other protections. The monthly instalment is only one part of the cost; the total repayment tells you what the borrowing really costs.
Consider a R20,000 purchase financed over 36 months. A lower monthly instalment can look easier than paying over 18 months, but the longer term keeps the debt alive for twice as long and can increase the total interest. This is why comparing credit requires the interest rate, fees, term and total amount payable, not only the monthly number printed in large text.
Different credit products create different risks. A home loan is secured by property, a vehicle loan may be secured by the car, while a credit card is usually unsecured and often charges a higher rate. Store accounts, overdrafts and personal loans may all behave differently. The name of the product matters less than understanding the obligation you are signing.
Credit records matter because lenders use past repayment behaviour as one input when deciding whether to lend again and at what price. Missing payments can therefore create two problems at once: immediate penalties and a weaker future borrowing position. Before taking credit, the strongest question is not “Can I afford the instalment this month?” but “Can my budget carry this commitment for the full term, even if life changes?”
APR and total repayment answer different questions
The rate helps compare borrowing cost, while total repayment shows the rand amount you may actually pay over the agreement.
Minimum payments can prolong debt
On revolving credit, paying only the minimum can keep a balance alive for a long time because interest continues to accrue.
Good credit is still debt
A strong credit score does not make borrowing free. It may improve access or pricing, but the repayment obligation remains.
Check your grasp of credit basics
Try this question using the ideas from this article. Open the explanation after choosing your answer.
Question 1
A store offers a lower monthly instalment if you repay over a longer period. What should you compare before accepting?
A. Only the monthly instalment
Show explanation
A small instalment can hide a longer repayment period and a higher total cost.
B. The total amount repaid, interest, fees and the agreement terms
Show explanation
Correct. Compare the full cost and conditions, not just the amount due each month.
C. Whether the item is advertised as affordable
Show explanation
Advertising language does not show the full borrowing cost.
Explain it in your own words
Why is credit not the same as extra income? Give one example of a cost that can be added to borrowing.
Compare with a model answer
Credit must be repaid under an agreement. Depending on the product, interest and fees may increase the total amount owed.
A smaller instalment can be the more expensive offer
Consider two hypothetical offers for the same purchase: R500 for 12 months and R350 for 24 months. Their instalment totals are R6,000 and R8,400. The smaller monthly figure has the larger total before any additional fees or insurance not already included.
That comparison does not identify the best contract by itself. Check the cash price, deposit, included charges, interest basis, term and any final payment. Also ask whether the instalment is affordable in a difficult month, not only the month in which you apply.
Borrow an amount to Compare total cost and affordability
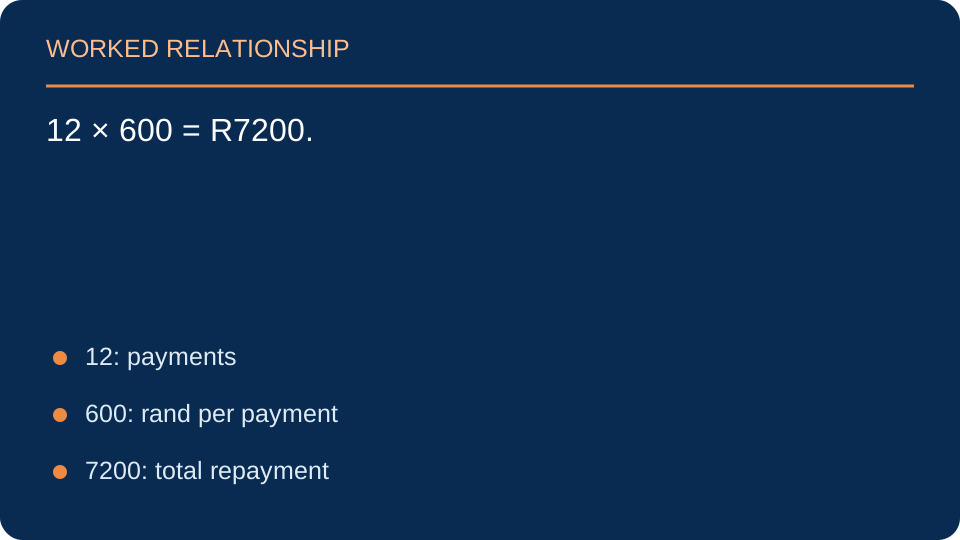
A fictional loan requires 12 payments of R600, with no separate charges. What total is repaid?
Trace the explanation
12 × 600 = R7200. Compare that with the amount borrowed, and check whether any charges sit outside the quoted instalment. A monthly amount alone hides the full commitment.
Source and further reading: National Credit Regulator
Why does paying on time not automatically mean a debt is shrinking quickly?
A payment may cover interest and fees before reducing much principal. What remains owed depends on the contract and payment schedule.
Read the statement's breakdown and compare the outstanding balance over time. Knowing where the payment went is more useful than assuming the full amount reduced the original loan.
Frequently Asked Questions
Common questions about credit
How is a credit score actually calculated?
Lenders weigh factors like payment history, how much of your available credit you use, and the length of your credit history.
What do lenders check before approving credit?
Your credit score, current income, existing debt and repayment history, to judge how likely you are to repay reliably.
Does using credit responsibly actually help my score?
Yes. Consistent on-time repayment and keeping balances low relative to your limit both tend to improve a credit score over time.
What happens if I only make minimum repayments?
The balance shrinks slowly while interest keeps accumulating, often making the debt take far longer and cost far more to clear.
What is a credit report?
It is a record held by a credit bureau containing information reported about credit accounts and repayment behaviour. Lenders can use it as part of a credit decision.
What is interest?
Interest is the price of borrowing, calculated according to the agreement. Fees can add additional cost, so compare the total instead of only the headline rate.
Does using credit build a history?
Responsible repayment can contribute to a positive credit record, but taking unnecessary debt solely to “build a score” can still cost money and create risk.
What should I ask before borrowing?
Ask what the total repayment will be, whether the instalment remains affordable if circumstances change, what fees apply and what happens if you pay early or miss a payment.
Sources
Sources and further reading
Look beyond the monthly repayment
Credit lets you use money or buy something now and repay later under agreed terms. The cost depends on more than the advertised interest rate. Fees, insurance, the repayment period, penalties, and the way interest is calculated can change the total amount you pay. Compare offers using the full agreement and total cost, not just the instalment that looks affordable today.
A simple example
If you borrow R5,000 and repay R500 per month for 12 months, the total instalments are R6,000. The difference is R1,000, before considering any fees or other charges that might apply. This example is only arithmetic, not a quote for a real loan. Actual repayments depend on the lender's terms and the timing of payments.
Why minimum payments can keep a balance alive
When a credit agreement allows a low minimum payment, part of the payment may go toward interest and fees before reducing the amount borrowed. If new purchases are added or the payment barely covers the cost of borrowing, the balance can take much longer to clear. Check the statement for the outstanding balance, interest, fees, due date, and how extra payments are treated.
Before signing
- What is the total amount payable over the full term?
- Which interest rate applies, and can it change?
- Are there initiation, monthly, insurance, or early-settlement charges?
- What happens if a payment is late or missed?
- Can you afford the instalment after essentials and irregular costs?
- Who can you contact if the agreement or a statement appears wrong?
Credit can help spread the cost of a necessary purchase, but it also commits future income. Be cautious of pressure to sign immediately or offers that do not clearly disclose the full terms. Never borrow based on the assumption that future income or bonuses are guaranteed.
Further reading: National Credit Regulator (South Africa) provides information about credit agreements and consumer rights. Check the current law and your specific agreement before making a financial decision.
What the minimum payment leaves behind
A repayment can cover charges and some principal while leaving most of the debt outstanding. Interest on the remaining balance can continue under the agreement's rules. Looking only at 'payment made' can hide slow progress on the amount originally borrowed.
The total-payment tool is deliberately simple: instalment multiplied by count, plus the deposit and any separately entered fees. It is not an interest-rate disclosure calculator. Use the lender's actual pre-agreement statement and the current National Credit Regulator information to understand a real offer.
Does approval establish that a loan is wise for your own goals?
No. Approval is the lender's decision under its assessment and rules. You still need to examine the total obligation, timing, risks and alternatives in your own budget.
Two offers have different monthly payments and different terms. What information would make the comparison meaningful?
One reasoned response
Compare total repayment, interest basis, fees, duration and early-settlement conditions. A lower instalment can result from paying for longer rather than borrowing more cheaply.
Source and further reading: National Credit Regulator
Read a credit statement before a problem grows
A statement is a record of how the lender says the account changed during a period. Check the opening balance, new purchases or advances, interest, fees, payments received, reversals and closing balance. If the numbers do not make sense, compare the statement with your receipts and payment confirmations and ask the provider for an explanation in writing.
Why the repayment term matters
Two offers can advertise similar monthly instalments but have different total costs because one runs for longer or includes additional fees. A smaller instalment can make a purchase feel affordable while committing income for more months. Compare the total amount payable, interest method, fees, insurance and consequences of missed payments before signing.
If you cannot pay on time
Contact the lender early using its official contact details. Ask what options exist, what they cost, and whether any agreement will be confirmed in writing. Avoid taking expensive new credit simply to cover an old payment without understanding the full effect. If you believe a charge is incorrect or you are being treated unfairly, keep records and consult the appropriate consumer-credit authority or adviser in your jurisdiction.
For South African consumers, the National Credit Regulator is a starting point for information about regulated credit and consumer rights. The correct response depends on the agreement and current law, so use official guidance rather than social-media promises.
A closer lookThe advertised instalment is only one line
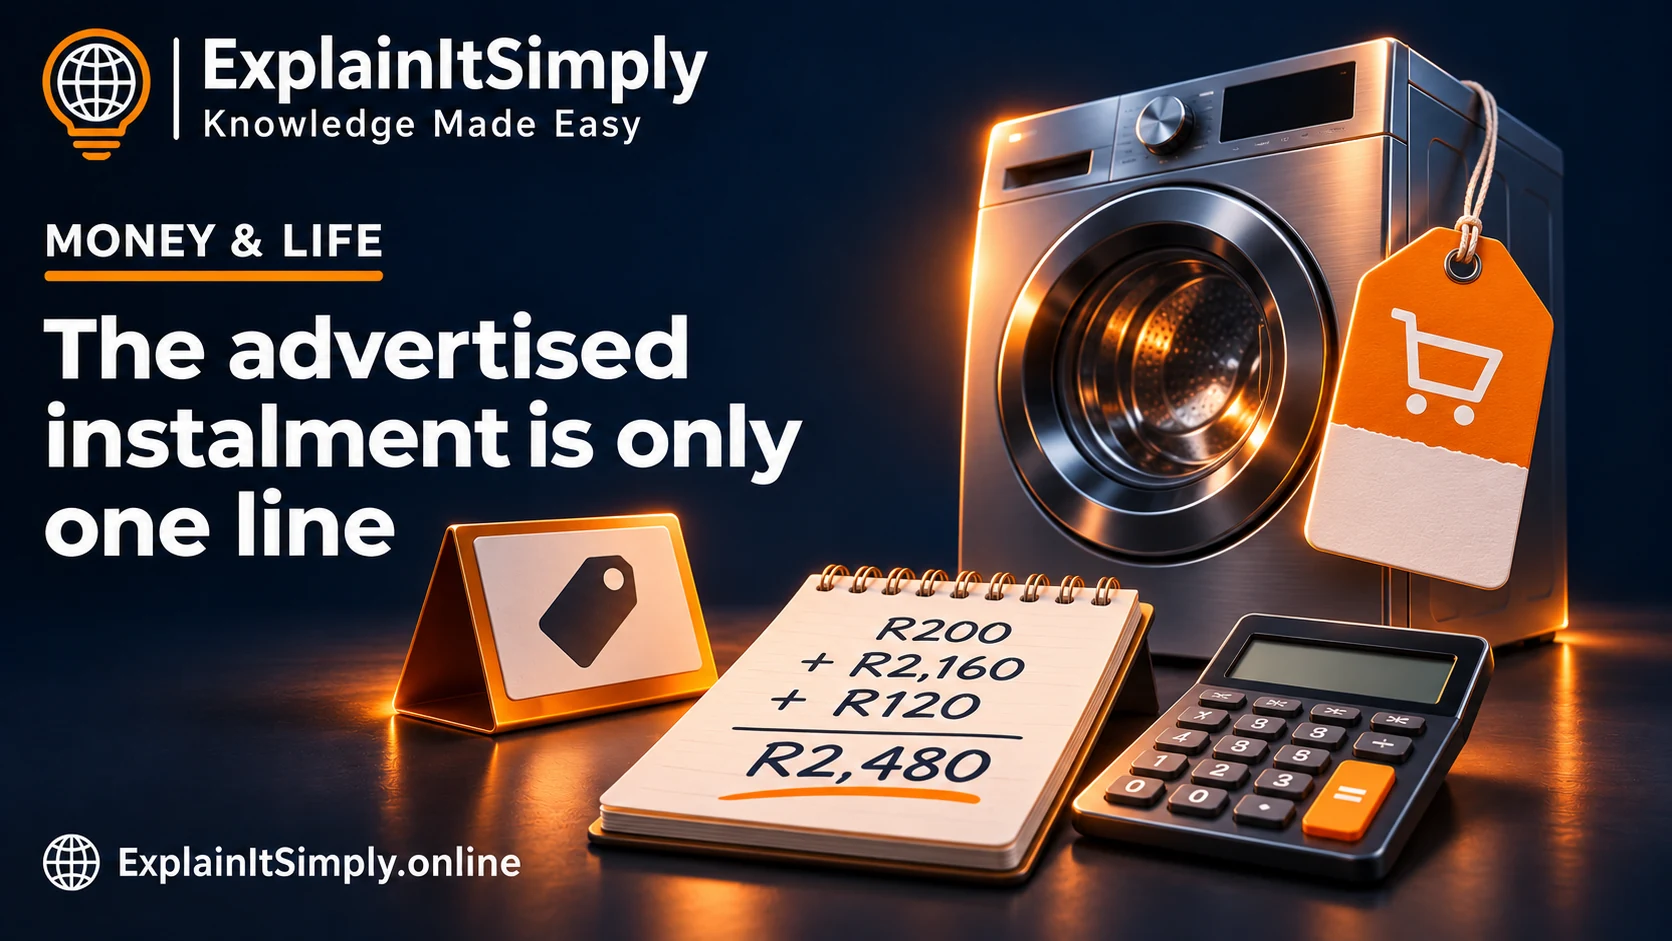
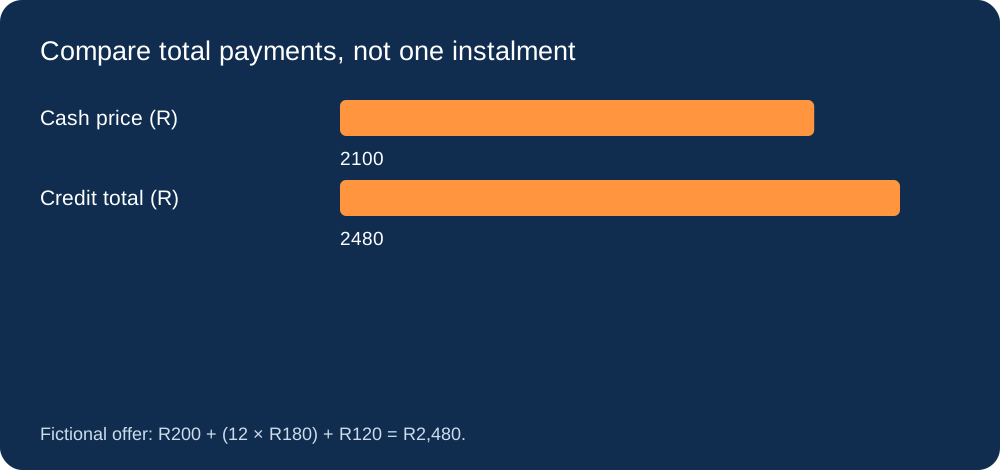
A fictional appliance offer asks for R200 upfront and R180 for 12 months, plus R120 in separately stated fees. The total of those payments is R2,480. A cash offer is R2,100.
Work through the distinction
Compare like-for-like totals: R200 + R2,160 + R120. Check whether fees are already included before adding them; double counting also misleads. This example is arithmetic, not a quotation of current lending terms.
What is the difference from the cash price?
Choose an answer to see feedback. You can try again.
Show the answer and explanation
R380 more. Compare like-for-like totals: R200 + R2,160 + R120. Check whether fees are already included before adding them; double counting also misleads. This example is arithmetic, not a quotation of current lending terms.