By Ronnie Mbuqe
A nominal return measures a change in money. Inflation changes what that money can buy, while fees and applicable taxes can reduce what the investor keeps.
Compare the result after relevant costs with the change in prices over the same period. A larger account number is only part of the outcome.
The short version
Investing allows your money to grow over time. By understanding Different types of investments and how they work, you can make smarter financial decisions.
Does a higher possible return mean a higher guaranteed return?
An investment's possible outcomes can vary, and fees and inflation affect what the result is worth.
Trace the explanation
A projection depends on assumptions. Distinguish a hypothetical calculation from a guaranteed future payment.
Source and further reading: www.investor.gov
Investing Means Accepting Uncertainty For A Possible Future Return
An investment is different from simply storing cash because you put money into an asset with the expectation that it may grow, produce income or both. That possibility comes with uncertainty. Shares can fall, property can lose value, businesses can fail and inflation can reduce the real value of low-return assets. There is no meaningful return discussion without a risk discussion beside it.
Time horizon changes which risks are reasonable. Money needed for school fees in three months should not depend on a volatile asset recovering from a sudden fall. Money intended for retirement decades away may have more time to ride through market cycles. The question “What should I invest in?” therefore starts with “When will I need this money and what happens if its value falls before then?”
Diversification reduces dependence on one outcome. Instead of relying on a single company, sector or country, a diversified portfolio spreads exposure. It cannot prevent all losses, because entire markets can fall together, but it lowers the chance that one company-specific disaster destroys the whole plan.
Compounding becomes powerful when returns stay invested and begin generating returns of their own. But fees compound too. A small annual fee difference may look harmless in one year yet remove a meaningful amount over decades. Investors should therefore understand costs, tax, liquidity and risk as carefully as they study headline performance.
Past performance is not a promise
An asset that performed well over the last five years can still perform poorly in the next five.
Risk has several forms
Price volatility is only one risk. There is also inflation risk, liquidity risk, concentration risk, credit risk and the risk of selling at the wrong time.
Real return matters
If an investment grows 6% while inflation is 5%, purchasing power has only increased by roughly 1% before fees and tax.
Check your grasp of investment basics
Try this question using the ideas from this article. Open the explanation after choosing your answer.
Question 1
An investment has delivered strong returns for the last three years. What does that tell you about next year?
A. It guarantees another strong return
Show explanation
Past performance cannot guarantee future results.
B. It is one piece of history, but future returns and losses remain uncertain
Show explanation
Correct. Consider risk, fees, diversification, time horizon and whether you can tolerate losses.
C. It means there is no risk left
Show explanation
Strong past returns do not remove investment risk.
Explain it in your own words
Why might money needed in six months be treated differently from money intended for a goal many years away?
Compare with a model answer
A short time horizon leaves less time to recover from a fall in value, so protecting money needed soon is often more important than seeking higher returns.
A steady-looking percentage is not a promise about next year
The compound-growth tool applies an invented constant annual rate so you can see the mechanism: a return left invested can itself earn later returns. Actual investments may fluctuate, lose value, charge fees and create tax consequences. The mathematical curve is not a forecast.
For R1,000 growing at an illustrative 5% annually, the first year ends at R1,050. Applying 5% again gives R1,102.50, because the second calculation includes the earlier R50. This is different from adding the same fixed amount every year.
Starting capital to Later returns apply to the new base
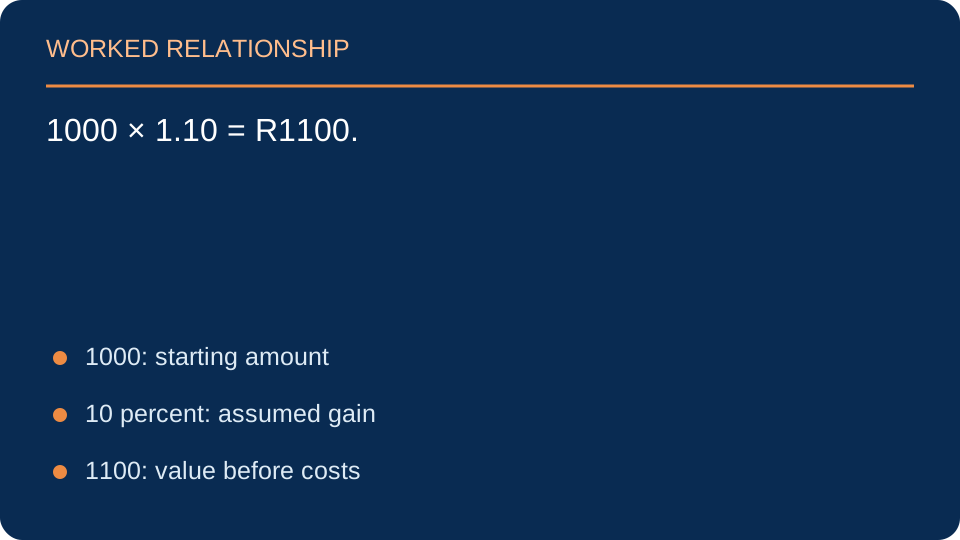
A hypothetical R1000 investment rises by 10 percent before fees. What is its new value?
Trace the explanation
1000 × 1.10 = R1100. This is arithmetic for one assumed positive return, not a forecast. A negative return, fees or taxes would produce a different result.
Source and further reading: www.investor.gov
Why can spreading money across several funds still leave one big risk?
Different funds may own many of the same assets or respond to the same economic forces. A count of fund names does not measure genuine diversification.
Look through to the underlying holdings and exposures. Diversification can reduce some concentration risks, but it cannot guarantee a positive return or eliminate every loss.
Frequently Asked Questions
Common questions about investments
What is the relationship between risk and return in investing?
Investments with higher potential returns generally carry higher risk of loss, so the two usually move together instead of separately.
How does time horizon affect what I should invest in?
Money needed soon is usually kept in lower-risk options, while money not needed for many years can typically absorb more short-term volatility.
What is diversification and Why Understanding Investments matters here
Spreading money across different investments so that a loss in one does not undermine your entire portfolio.
What is a common mistake new investors make?
Reacting to short-term price swings by buying or selling emotionally, instead of sticking to a plan matched to their time horizon.
What is diversification?
It means spreading investments across different assets, sectors or markets so one poor result has less effect on the whole portfolio.
What is compound growth?
Returns can themselves earn future returns when gains remain invested. Over long periods this can materially change the outcome, but losses and fees compound too.
Why do fees matter?
Investment fees reduce the amount that stays invested. A small annual fee difference can become significant over many years.
Should emergency savings be invested?
Emergency money usually prioritises stability and access. Investments that can fall sharply may force you to sell at a bad time when an emergency occurs.
Sources
Sources and further reading
Match an investment to the goal and the time available
Investing means putting money into an asset with the expectation that it may grow or produce income. The return is uncertain, and the value can fall. Before comparing products, separate money needed soon from money you can leave invested for longer. A goal due next month usually cannot tolerate the same uncertainty as a retirement goal decades away.
Three factors to compare
Time horizon: when will you need the money? A longer period can provide more time to recover from some market declines, but it does not guarantee a profit. Risk: how much loss could you tolerate financially and emotionally without abandoning the plan? Fees: what charges apply when buying, holding, switching, or selling? Fees reduce the amount that remains invested and can compound over time.
Understand diversification
Putting all your money into one company or one type of asset concentrates risk. Diversification spreads exposure across different investments, though it cannot remove every risk or prevent losses in a broad market decline. What counts as diversified depends on what the investment actually holds, not only the name of the product.
Beware of guaranteed-return claims
High returns with no risk are a warning sign. Check whether the provider is authorised where required, understand how withdrawals work, and read the product documents. Do not invest money you need for rent, food, debt repayments, or an imminent expense just because a promotion says the opportunity is limited. Never rely on screenshots of profits as proof of a legitimate investment.
A simple pre-investment checklist
- What goal is this money for, and when is it needed?
- What could make the investment lose value?
- What are the total fees and tax implications?
- Can I explain how the product earns or loses money?
- Can I access the money when needed?
- Have I checked the provider and offer independently?
This guide is general education, not personal investment advice. Your circumstances, tax position, and risk tolerance matter; seek appropriately qualified advice for decisions you are unsure about.
Further reading: Financial Sector Conduct Authority; South African Reserve Bank.
The date you need the money changes the question
Money needed for a near-term essential payment has a different tolerance for loss and delay from a long-term goal. A volatile asset may fall just before you need to sell. Access restrictions can also matter even if a quoted return looks attractive.
Compare liquidity, possible loss, fees and diversification alongside expected return. Diversification spreads exposure but does not guarantee a profit. Before using a real product, verify the provider and understand the actual terms; an attractive graph or an unsolicited message is not due diligence.
If an investment falls 50%, does a later 50% gain restore the starting value?
No. R100 falls to R50, then a 50% gain adds R25, reaching R75. Percentages apply to the changed base; a 100% gain from R50 would restore R100.
A promotion shows only its best year's return. What evidence would you ask for?
One reasoned response
Ask about losses, fees, the full period, the benchmark, liquidity and how the product is regulated. One successful period cannot establish the range of future outcomes.
Source and further reading: www.investor.gov
Match the investment to the time you can leave it alone
Before comparing investments, identify when you may need the money. Money required soon for rent, fees or an emergency usually cannot tolerate the same uncertainty as money intended for a distant goal. An investment that might recover after a market fall may still be unsuitable if you must sell during that fall to pay an immediate bill.
Compare risk, fees and diversification
- Risk: what could cause the value or income to fall, and how large could the loss be?
- Fees: what do you pay to buy, hold, manage or sell it? Small annual fees can compound over long periods.
- Diversification: does the investment depend heavily on one company, asset, sector or country?
Be careful with performance claims
Past returns do not guarantee future results. A chart may exclude fees, taxes, inflation or losing periods. Compare like with like and read the official product documents. Be especially cautious when someone promises high returns with little or no risk, pressures you to act immediately, or asks you to pay into an account that cannot be independently verified.
This page explains general concepts, not a recommendation to buy a particular product. Check the provider's regulatory status and consider independent qualified advice for decisions that could materially affect your finances. Keep short-term emergency money separate from investments whose value can fluctuate.
A closer lookA gain before costs is not the final result
An illustrative R1,000 investment rises by R80, then incurs R20 in stated costs. It ends at R1,060 before any tax. If a comparable basket of goods rises by 7 percent, that basket now costs R1,070.
Work through the distinction
Distinguish a positive rand return from preserving purchasing power. This single-period example ignores distributions and tax and assumes the cost is charged after the gain. It is not a forecast or a product recommendation.
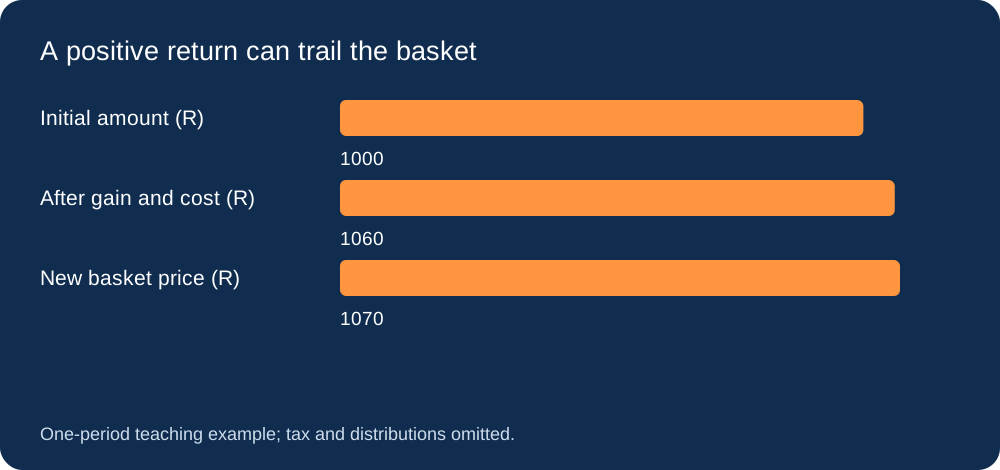
Does R1,060 buy the same R1,070 basket?
Choose an answer to see feedback. You can try again.
Show the answer and explanation
No, despite the positive rand return. Distinguish a positive rand return from preserving purchasing power. This single-period example ignores distributions and tax and assumes the cost is charged after the gain. It is not a forecast or a product recommendation.