By Ronnie Mbuqe
Many choices create later payments: interest, maintenance, renewal fees or replacement costs. Comparing only the first payment leaves those commitments out.
For a hypothetical device, list purchase, service and recurring costs over the same period for each option. The comparison becomes meaningful only when the boundaries match.
Start with the plain-language version
How Money Works
Understand money flow: earning, spending, and saving strategies for financial freedom.
Read Article
What Is Credit?
Learn why credit scores matter, how to build them, and how to avoid debt traps.
Read Article
Saving vs Spending
Learn to balance short-term enjoyment and long-term financial security.
Read Article
Understanding Investments
Learn how to grow wealth through stocks, bonds, ETFs, and long-term strategies.
Read Article
Budgeting Basics
Track income, manage expenses, and set achievable financial goals.
Read Article
Insurance Basics
Protect yourself and your family: health, life, property, and liability insurance essentials.
Read Article
Taxes Made Simple
Learn the basics of filing taxes, deductions, and staying compliant.
Read Article
Side Hustles
Explore ways to earn extra income, develop new skills, and diversify your career opportunities.
Read Article
Key Takeaways
- Start building financial literacy early: budget, save, invest, and track your credit.
- Protect yourself with insurance and understand the basics of taxes.
- Develop digital literacy, negotiation, and decision-making skills to navigate modern life.
- Experiment with side hustles and multiple income streams.
- Lifelong learning is essential: life skills evolve as society changes.
Explore practical money decisions
Why can a small repeated expense matter more than a memorable once-off purchase?
A single payment attracts attention, while repeated spending can pass unnoticed.
 Original ExplainItSimply illustration; conceptual, not a scale drawing.
Trace the explanation
Converting costs to the same period makes comparisons fairer. The point is to see the trade-off, not to declare every small pleasure wasteful.
Source and further reading: Consumer Financial Protection Bureau
A monthly price is a fragment of a financial decision
An instalment, a premium and a savings contribution all look like monthly amounts, but they create different rights and obligations. To compare them, ask what is being paid for, how long the commitment lasts and what happens if circumstances change.
The guides begin with everyday choices and follow the mechanism: cash-flow timing, borrowing cost, cover conditions and uncertain returns. Worked rand examples are illustrative rather than quotations for a real product. Current South African tax and credit requirements link back to official sources.
Name the decision and date to Compare outcomes under stated assumptions
Money and life decisions become easier when you can see the trade-offs
Personal finance is not only about earning more money. It is about deciding how today's choices affect tomorrow. Spending gives you something now, saving protects future options, credit brings future income forward, insurance transfers certain risks, and investing accepts uncertainty in exchange for the possibility of growth.
These ideas connect. A budget creates room for saving; an emergency fund can reduce the need for expensive credit; understanding interest helps you compare both loans and investments; knowing your risks helps you decide what insurance is actually useful.
This section is designed to help you follow those connections so that each money topic becomes part of one practical picture instead of a list of financial terms.
Why does a percentage need a base before it means anything useful?
A percentage describes a proportion of some amount. The same rate applied to a different base gives a different rand result.
Ten percent of R100 is R10; ten percent of R1,000 is R100. When reading a fee or discount, ask which amount the percentage uses and when it applies.
Practical examples: Life
At the till or checkout
A purchase affects more than the balance shown today. Paying cash, using a debit card, taking store credit or choosing instalments changes fees, future obligations and the amount available for other needs. Understanding the full cost helps a shopper compare choices instead of looking only at the first payment.
When income arrives
Salary day is where budgeting becomes real. Rent, transport, food, debt, school costs and irregular expenses may already have claims on the money. A plan makes those promises visible before small purchases quietly use what was meant for something important.
Before signing an agreement
Loans, insurance and service contracts use terms such as interest, excess, exclusion, cancellation fee and waiting period. Knowing what each term changes helps a person ask what the agreement costs in total and what happens when circumstances change.
When planning for risk
An emergency fund, insurance and careful borrowing solve different problems. Comparing the likelihood of a loss, how large it could be and whether you could pay for it yourself helps you choose protection deliberately instead of from fear or sales pressure.
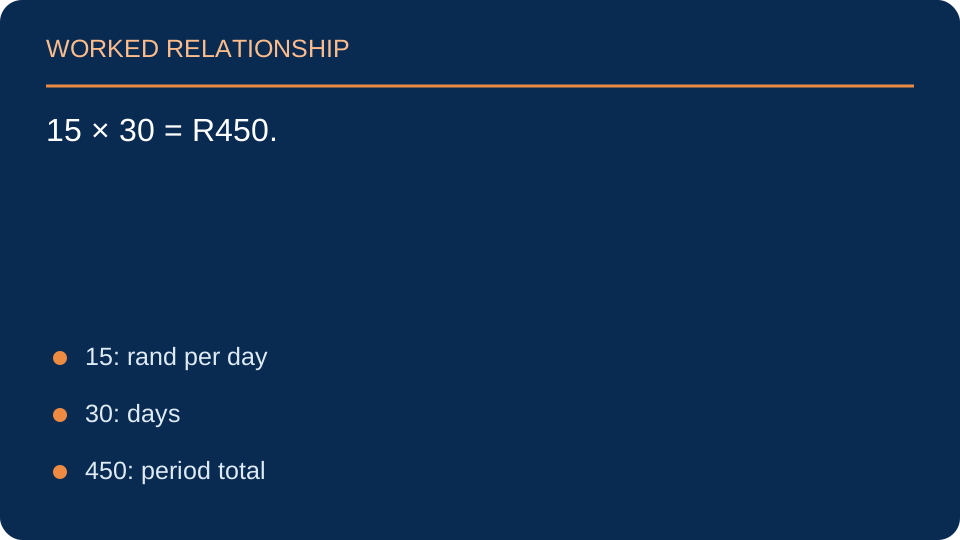
A fictional service costs R15 each day for 30 days. What is the total?
Trace the explanation
15 × 30 = R450. Compare that monthly total with the value the service provides and the other uses of the money. An annual or weekly comparison needs its own consistent period.
Source and further reading: Consumer Financial Protection Bureau
Frequently Asked Questions
Questions about Life Basics
Where should I start learning about personal finance?
Budgeting is usually the best starting point, since it shows where your money actually goes before you tackle credit, saving or investing.
How are credit, saving and investing connected?
Credit borrows from future income, saving protects against short-term needs, and investing grows money over a longer time horizon, each serves a different purpose.
What is the biggest mistake people make with money?
Not tracking where money actually goes, which makes it hard to notice small leaks that add up over months.
Do I need to understand investing before I start saving?
No. Building a basic emergency fund and steady saving habit comes first; investing knowledge can follow once that foundation exists.
Money In Real LifeMoney Decisions Are Connected
A budget, a bank account, credit, insurance, tax and investing can look like separate topics. In real life they form one system. Income arrives, some is committed to essentials, some may repay debt, some protects against emergencies, and some can be saved or invested for later. A decision in one area changes what is possible in another.
Say a household earns R20,000 after deductions. If fixed expenses take R13,000 and debt repayments take R4,000, only R3,000 remains before food surprises, repairs or savings. The useful question is not simply “Do I earn enough?” but “Where is my money already promised before I make a new decision?” That is why cash flow is often more revealing than salary alone.
Price And Cost Are Not Always The Same
A R10,000 item bought with credit can cost more than R10,000 after interest and fees. A cheap insurance policy can become expensive if the cover is too limited when a claim happens. An investment with a high advertised return can be a poor choice if the risk, fees or time horizon do not fit the goal. Good money decisions compare the full consequence, not only the number printed largest on the page.
These guides are educational, not personal financial advice. Their purpose is to help you ask better questions: What will this cost in total? What happens if my income stops? What am I giving up by choosing this? What risk am I accepting? Once those questions become a habit, financial products become easier to evaluate.
Questions To Ask Before A Money Decision
Should I save while I still have debt?
It depends on the debt cost and your need for an emergency buffer. Many people benefit from having some accessible emergency money while also prioritising expensive debt.
Is the cheapest option always best?
No. Compare what you receive, the risks, fees, exclusions, durability and total cost over time.
Why do small monthly payments become dangerous?
Because several small commitments can quietly consume most of future income. Looking at the combined monthly total and total repayment cost makes the obligation visible.
Use a calculator to inspect an assumption, not to hide it
A compound-growth curve assumes a rate; a total-payment calculation assumes the instalment count and included fees. Change those assumptions and watch the result. A precise-looking answer can still describe the wrong contract if the inputs omit an important payment.
For an immediate shortfall, begin with budgeting and dates. For a purchase funded by borrowing, compare the full credit obligation. For money you will need later, separate saving for a known bill from taking investment risk. The right route begins with the decision and deadline, not the most exciting percentage.
Does a calculator's two-decimal answer make its assumptions true?
No. Arithmetic precision is different from accurate inputs and an appropriate model. Check what the tool includes and leaves out.
You want to reduce spending without guessing. What would you record for a week?
One reasoned response
Record amount, purpose and frequency, including automatic payments. Group the records afterward so decisions are based on actual patterns rather than the most memorable transaction.
Source and further reading: Consumer Financial Protection Bureau
Money in real lifeGood money decisions begin by understanding what happens after the payment
A price tells you what something costs today, but many financial decisions continue for months or years. Credit adds interest and fees. Insurance trades a regular premium for protection against a larger loss. Investing accepts uncertainty in exchange for the possibility of future growth. Taxes fund public services and affect the amount of income you can actually use.
This section uses everyday situations instead of financial jargon. A budget is explained as a plan for money before it disappears into small purchases. Credit is followed from the amount borrowed to the total repaid. Saving and investing are compared by purpose, time and risk instead of being treated as the same thing.
Ask what it costs in total
Monthly affordability matters, but the full repayment, fees and time commitment can change whether a deal is good for you. Looking beyond the first payment is one of the most useful money habits.
Build decisions around real priorities
A useful budget makes room for essentials, irregular costs and goals before optional spending. The aim is not perfection. It is knowing where your money is going and choosing deliberately.
Sources and further reading
A closer lookPut the decisions on one household timeline
A budget, a saving goal and a repayment all draw on the same income. Place their amounts and dates together before treating each as affordable separately.
Work through the distinction
Start with predictable obligations, then uncertainty and goals. Use fictional examples to understand the arithmetic and current official or provider information for actual decisions. Avoid entering identifying financial information in public comments.
Why combine the decisions?
Choose an answer to see feedback. You can try again.
Show the answer and explanation
They compete for the same income. Start with predictable obligations, then uncertainty and goals. Use fictional examples to understand the arithmetic and current official or provider information for actual decisions. Avoid entering identifying financial information in public comments.