By Ronnie Mbuqe
A deposit is a recorded claim on the bank, used within a wider payment and banking system. Paying electronically changes financial records rather than physically moving a matching packet of notes.
The app is your view of those records. Settlement, account rules and available funds determine what a transfer actually does.
Before going deeper
Money is a tool. Understanding how it works is the first step to using it well and building long-term financial stability.
Why does accepting money depend partly on trusting other people will accept it?
Money helps people compare prices, exchange goods and carry purchasing power across time.
Trace the explanation
Those functions depend on acceptance and the monetary system. The number printed on a note is not a guarantee that it will buy the same basket forever.
Source and further reading: www.resbank.co.za
Money Works Because People Trust A Shared System
Money is useful because it solves three problems at once: it gives us a common way to measure value, a convenient way to exchange value, and a way to carry purchasing power from today into the future. Without money, every trade would require two people to want exactly what the other person has at the same time. Money removes that matching problem.
Modern money is mostly not notes and coins. When your salary arrives, your bank normally changes numbers in an account ledger. When you tap a card at a shop, several systems exchange messages: the merchant asks whether the payment can be authorised, networks route the request, your bank checks the account and risk signals, and approved balances are later settled between financial institutions. The physical cash may never move.
This system works because institutions and users accept the unit of account. In South Africa, prices, salaries and debts are expressed in rand. The Reserve Bank, commercial banks, payment networks, laws and confidence in the economy all help support the system. Trust does not mean the value is fixed forever; inflation can reduce what the same amount buys over time.
Banks also connect savers and borrowers. Deposits provide part of the funding banks use in the wider financial system, while loans allow households and businesses to spend or invest before they have saved the full amount. Interest becomes the price for using money over time and for taking credit risk. This is why changes in interest rates can affect home loans, vehicle finance, saving returns and business investment across the economy.
Your bank balance is a record
For most people, money in a bank account is a claim recorded by the bank instead of a pile of notes stored in a box with your name on it.
Inflation changes purchasing power
If prices rise faster than your money grows, the same R1,000 buys less in future even though the number printed on the account has not changed.
Payments are messages plus settlement
A card payment feels instant to you, but behind it are authorisation messages, fraud checks, clearing and final movement of funds between institutions.
A bigger number can buy fewer things
Imagine a basket costs R100 and later costs R110. Holding R105 gives you more rand than before but still not enough for that basket. The distinction is between a nominal amount and purchasing power: what the amount can actually obtain.
This example uses an invented basket, not a current inflation rate. Different households buy different goods, so one person's experience need not match a single published average. Compare like-for-like items and time periods before drawing a conclusion from changing prices.
A money amount to The quantity you can buy
Why can money keep the same number while buying less?
Prices describe how much money exchanges for goods and services. If the price of a familiar basket rises, an unchanged amount buys less of that basket.
If a fictional item rises from R20 to R25, R100 buys four instead of five. That example illustrates purchasing power, rather than predicting any particular price increase.
Check how money systems fit together
Try this question using the ideas from this article. Open the explanation after choosing your answer.
Question 1
A shop raises the price of a loaf of bread from R15 to R18. What has changed?
A. The rand note itself has changed
Show explanation
A banknote has not changed; the price of this item has.
B. The loaf now costs R3 more, so the same R15 buys less bread
Show explanation
Correct. The price rose by R3. If you have only R15, it no longer buys the same loaf at the new price.
C. All money has become worthless
Show explanation
No. A price increase for one item does not mean all money has become worthless.
Explain it in your own words
Explain in your own words why having R1,000 in an account does not always mean you can buy the same amount of goods next year.
Compare with a model answer
The balance may remain R1,000, but if prices rise, that money may buy fewer goods. The account balance and purchasing power are different ideas.
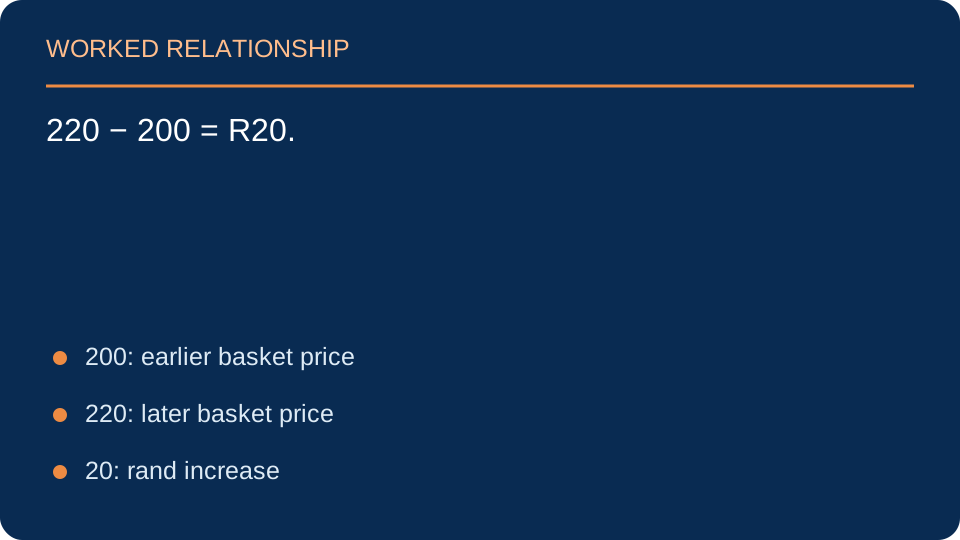
A fictional basket costs R200 and later R220. By how many rand has its price increased?
Trace the explanation
220 − 200 = R20. That is also 10 percent of the original R200. One basket's change illustrates purchasing power but does not establish an official economy-wide inflation rate.
Source and further reading: www.resbank.co.za
Frequently Asked Questions
Common questions on how money works
Why does money have value if it is not backed by gold?
Because enough people and institutions agree to accept it in exchange for goods, services and debts, and trust that others will too.
What determines whether prices go up or down?
The balance between how much buyers want something and how much of it sellers are willing to supply at a given price.
How do banks fit into how money moves?
Banks hold deposits, record transactions and lend a portion of that money out, which is part of how money circulates through an economy.
Why do interest rates affect everyday spending?
Higher rates make borrowing and saving more expensive and more rewarding respectively, which changes how much people spend versus save.
Why do banks show money digitally if cash is real?
Most modern money is represented as account balances and electronic records. Cash is one form of money, but electronic payments can transfer claims between financial institutions without physical notes changing hands.
What is the difference between saving and investing?
Saving usually prioritises safety and access for near-term needs. Investing accepts more uncertainty in exchange for the possibility of higher long-term growth.
Why does borrowing cost money?
Lenders charge interest and sometimes fees because they provide funds now, take the risk of non-payment and give up the use of that money during the loan period.
What should I understand first?
Start with cash flow: what reliably comes in, what must go out, which costs can change and what future commitments already exist.
Sources
Sources and further reading
Why transferring money is not the same as moving banknotes
A digital payment changes records and obligations across participating systems. The customer sees a balance, while institutions handle the rules and processes behind the transfer. An instruction being submitted is not always the same event as final settlement or the recipient seeing usable funds.
That is why reference numbers, dates and payment status matter. Before repeating an uncertain transfer, check the authoritative record through the provider's official channel. The absence of an immediate notification does not prove the first instruction did nothing.
If income rises by 5% and the same basket rises by 10%, has purchasing power increased?
For that basket, it has decreased. Compare the ratio 1.05 ÷ 1.10, not just the positive salary percentage. Actual household outcomes depend on the costs and income involved.
You have more rand than last year but can buy fewer groceries. What two quantities should you compare?
One reasoned response
Compare your money amount with relevant prices. A higher nominal amount can coexist with lower purchasing power if prices have risen faster.
Source and further reading: www.resbank.co.za
Follow the payment chain
Money is useful because people accept it as a way to pay, compare prices, and hold value for later. In an everyday purchase, several steps sit behind the moment you tap a card or send a transfer: the payer authorises the payment, a bank or payment provider checks it, payment instructions move between systems, and the recipient's account is credited according to the service's rules. A displayed confirmation and final settlement are related, but not always the same instant.
Four jobs money does
- Medium of exchange: it lets people trade without finding someone who wants exactly what they offer.
- Unit of account: prices give a common way to compare different goods and services.
- Store of value: money can carry purchasing power into the future, although inflation can reduce what it buys.
- Means of deferred payment: prices and debts can be stated in money for payment later.
Why a payment can fail
A transaction may be declined because of insufficient funds, incorrect details, security checks, a daily limit, a network problem, or a recipient account issue. A pending transaction may still be processed or reversed depending on the payment method. Before paying again, check the transaction history and the provider's guidance so you do not accidentally pay twice.
Inflation and purchasing power
If a basket of goods costs R100 this year and R106 next year, that basket has become 6% more expensive. If your income does not rise, the same amount of money buys less of that basket. Inflation does not mean every price rises by the same amount; your personal experience depends on what you buy.
Practical money habits
Keep a record of recurring payments, check statements, use strong authentication, and never share a one-time PIN with someone who contacts you unexpectedly. Verify payment notifications inside your own banking app rather than trusting a screenshot from a buyer. If a transfer or debit looks wrong, contact the provider through an independently verified channel.
Further reading: South African Reserve Bank explains money and monetary policy; Financial Sector Conduct Authority provides consumer information about financial services.
A closer lookMore rand, fewer groceries
A basket costs R200 and later costs R220. A R210 budget used to buy the basket with R10 left; now it is R10 short. The money amount increased relative to R200, but not enough to match the price.
Work through the distinction
Compare purchasing power using the same basket. A single basket illustrates the idea but is not a national inflation measure: households buy different goods and prices change at different rates.
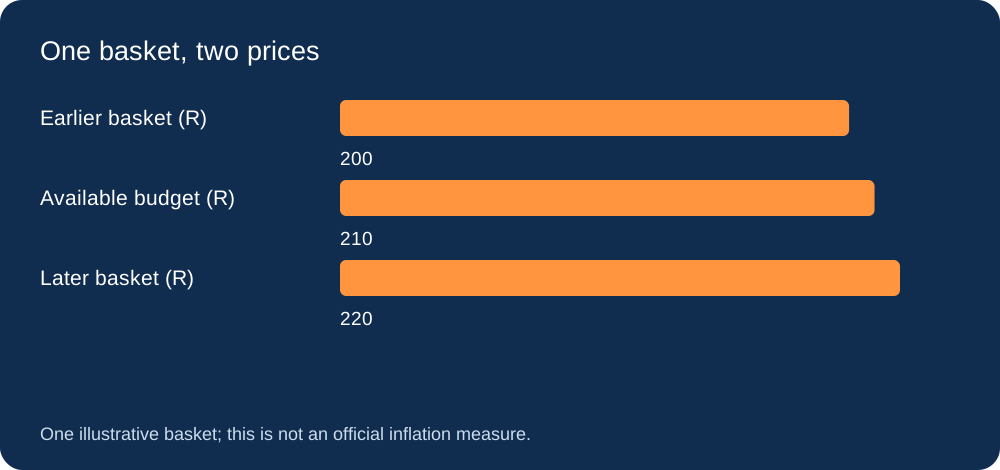
Can R210 buy the new R220 basket?
Choose an answer to see feedback. You can try again.
Show the answer and explanation
No, it is R10 short. Compare purchasing power using the same basket. A single basket illustrates the idea but is not a national inflation measure: households buy different goods and prices change at different rates.