By Ronnie Mbuqe
A policy defines covered events, limits, exclusions and the insured person's responsibilities. Having insurance is different from having every possible loss fully covered.
Use a specific scenario and read the relevant wording, including any excess. The premium is the price of the contract, not a summary of its protection.
The idea in everyday language
Insurance provides a safety net. It allows you to transfer risk to a company that can handle it financially. This includes health emergencies, property damage, accidents, and even loss of life income.
Common Types of Insurance
1. Health Insurance
Helps cover medical expenses, doctor visits, medications, surgeries, and preventive care. Protects you from high healthcare costs.
2. Life Insurance
Provides financial support to your dependents if you pass away. Term life covers a specific period, while whole life combines coverage with investment growth.
3. Property Insurance
Protects your home, car, or other valuable possessions against damage, theft, or natural disasters. Includes homeowners, renters, and auto insurance.
4. Liability Insurance
Covers you if you are legally responsible for injuries or damages to someone else. Includes general liability and professional liability.
5. Disability Insurance
Provides income if you cannot work due to illness or injury. Helps maintain financial stability when you cannot earn a paycheck.
Tips for Choosing Insurance
- Understand your risks and what matters most to protect.
- Compare policies and coverage carefully.
- Check deductibles and premium costs to balance protection and affordability.
- Read the fine print to avoid surprises when making a claim.
- Review policies regularly as your life situation changes.
Insurance and Financial Planning
Insurance isn’t just a safety net; it’s part of a smart financial strategy. It ensures you don’t lose hard-earned assets to unexpected events, allowing your savings and investments to grow with less risk.
Conclusion
Understanding insurance basics is a key life skill. By learning about different policies and planning your coverage, you protect your future and the people you care about.
Before you choose or renew
- Check what events and items are covered, and what is excluded.
- Compare the excess you would have to pay when making a claim.
- Check waiting periods, claim limits and any conditions you must meet.
- Make sure the information you give the insurer is complete and accurate.
- Ask the insurer to explain anything unclear, and keep the answer with your policy documents.
A policy is useful only when its terms match the risk you need to manage. Read the policy wording and confirm details directly with the insurer before deciding.
Key Takeaways
- Start building financial literacy early: budget, save, invest, and track your credit.
- Protect yourself with insurance and understand the basics of taxes.
- Develop digital literacy, negotiation, and decision-making skills to navigate modern life.
- Experiment with side hustles and multiple income streams.
- Lifelong learning is essential: life skills evolve as society changes.
Does having insurance mean every loss will be paid in full?
Insurance transfers specified risks under a contract.
Trace the explanation
Exclusions, limits and excesses affect what is payable. Read the event being insured and the conditions rather than treating the word covered as an unlimited promise.
Source and further reading: www.fsca.co.za
Insurance Trades A Certain Small Cost For Protection Against A Large Uncertain Loss
Insurance pools risk. Many customers pay premiums into a system, while only some experience the insured event during a given period. The insurer uses pricing, reserves and reinsurance to make sure it can pay valid claims while remaining financially sustainable.
The policy wording defines the promise. Two products both called “car insurance” may cover different events, excess amounts, drivers, territories or replacement conditions. The price only makes sense beside the coverage. A cheaper premium can be poor value if important risks are excluded or the excess is unaffordable.
The excess is the portion of a claim you agree to carry yourself. If damage is R20,000 and the policy excess is R5,000, the insurer may pay the covered balance subject to the policy terms. A higher excess often reduces the premium because you are retaining more of the risk.
Insurance works best for losses that would seriously damage your finances. Small predictable expenses can often be budgeted for directly. The question is whether you could absorb the loss yourself without destroying your financial plan.
Disclosure affects claims
If an insurer prices a policy using false or missing important information, the claim can become disputed later.
Underinsurance can reduce payouts
Some policies require assets to be insured for an appropriate value and can reduce claims when the declared value is too low.
Claims history influences pricing
Insurers use risk information, including claims patterns, to estimate the likelihood and cost of future claims.
Having a policy and having this event covered are different facts
An insurance contract defines insured events, exclusions, limits and conditions. The everyday phrase 'my phone is insured' is not enough to know whether loss, accidental damage or a particular use is covered. Read the schedule together with the policy wording.
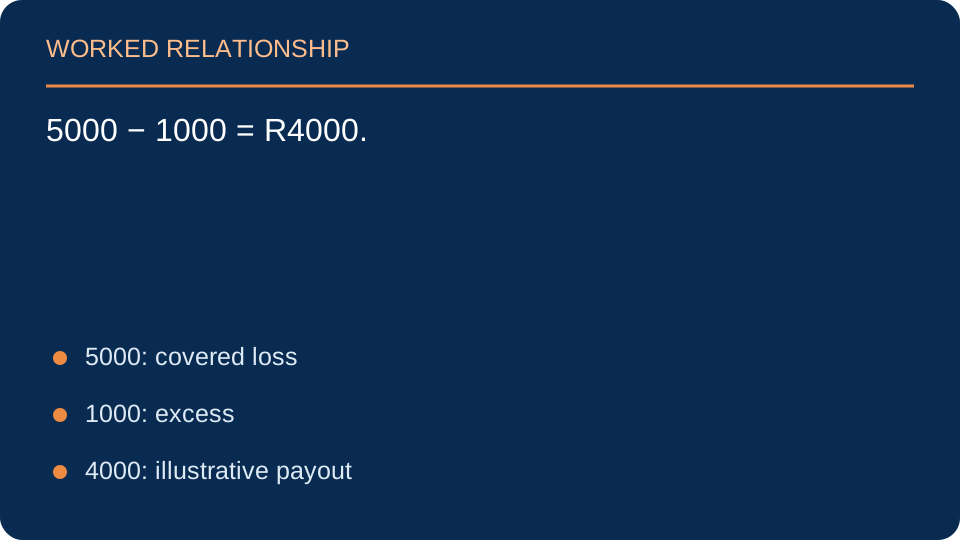
Suppose a covered R5,000 loss has a R1,000 excess and no other limitation in this simplified example. The excess means part of the loss remains yours. Actual settlement can also depend on limits, valuation and other terms, so the subtraction is an illustration, not a claim promise.
An event occurs to Evidence and limits determine settlement
Why is the cheapest premium not a complete comparison?
Two policies can charge differently because they cover different events, limits or excesses. A lower regular cost can come with more out-of-pocket exposure.
Compare the same situation under both contracts. Ask what would be paid, what evidence is required and which amount remains yours to cover.
A worked example and a common mix-up
A practical example
A vehicle policy has an excess of R5,000. If a covered repair costs R35,000, the insurer may pay the covered amount above the excess according to the policy. If a scratch costs R3,000, a claim may not help because the cost is below the excess. Understanding that before an accident prevents surprise.
A common misunderstanding
Insurance is not a savings account where you are entitled to get all your premiums back if nothing happened. The value is the transfer of specified risk during the period of cover.
A fictional covered loss is R5000 with a R1000 excess and no other limits. What would the insurer pay in this simplified case?
Trace the explanation
5000 − 1000 = R4000. Real policies may apply additional conditions, limits or valuation rules. The example illustrates an excess, not an entitlement under a particular policy.
Source and further reading: www.fsca.co.za
Check your grasp of insurance basics
Try this question using the ideas from this article. Open the explanation after choosing your answer.
Question 1
Two vehicle policies have similar premiums, but one has a much higher excess and excludes a risk you care about. What should you do?
A. Choose the cheaper premium immediately
Show explanation
The premium alone does not show what you would pay or whether the risk is covered.
B. Compare exclusions, excesses, limits and conditions as well as premiums
Show explanation
Correct. Read the policy wording and check whether the cover fits your needs and ability to pay the excess.
C. Assume both policies will pay the same claim
Show explanation
Different terms can lead to different claim outcomes.
Explain it in your own words
In your own words, explain why a low monthly premium does not automatically mean an insurance policy is better value.
Compare with a model answer
A low premium may come with a higher excess, exclusions, lower limits or conditions that affect whether a claim is paid.
What would you need to show after something goes wrong?
Keeping suitable proof of ownership and an accurate description of the event can make a claim easier to assess. The required evidence and deadlines depend on the contract and circumstances. Inventing a detail to strengthen a claim creates a different and serious problem.
When comparing policies, consider what loss you could absorb yourself and what loss would disrupt your life. A low premium can accompany narrower cover or a larger excess. Compare the same event across the options, then ask how each would actually respond, rather than comparing monthly prices alone.
Does paying premiums guarantee every submitted claim will be paid?
No. The event must meet the contract's cover and conditions. If a claim is rejected, ask for the written reason and use the applicable complaint process rather than assuming the premium purchased unlimited cover.
Common questions on insurance
What does insurance actually protect against?
A specific, defined risk named in the contract; it does not cover every possible danger, only what the policy explicitly lists.
What is an excess and Why Insurance Basics matters here
It is the amount you pay yourself before the insurer covers the rest of a claim, a higher excess usually means a lower premium.
Why do insurance claims sometimes get rejected?
Usually because the situation falls outside what the policy covers, or because required conditions, like disclosures, were not met.
How do I know how much cover I actually need?
Estimate the real financial impact of the risk you are insuring against, then compare that to what different policies would pay out.
What is an excess?
It is the portion of a covered claim that the policyholder must pay, subject to the policy terms.
What is an exclusion?
It is a situation, cause or type of loss that the policy does not cover. Read exclusions before relying on the cover.
Why do premiums change?
Prices can change because of claims experience, inflation, asset value, risk factors, market conditions or changes in the cover.
What does underinsurance mean?
It can occur when an insured value is too low relative to what the policy requires, potentially reducing a claim. The exact effect depends on the policy wording.
What is the difference between insurance and a warranty?
Insurance generally covers specified uncertain losses; a warranty usually promises repair or replacement for defects under defined conditions.
Should I choose the lowest premium?
Compare the insured events, exclusions, excesses, limits and service as well as price. The cheapest product may not protect the risk you actually care about.
Two policies have different premiums. What would you compare before choosing the cheaper one?
One reasoned response
Compare the insured events, exclusions, limits, excesses and claims requirements. Lower cost may accompany less protection; the useful question is which risks each contract actually transfers.
Source and further reading: www.fsca.co.za
Sources
Sources and further reading
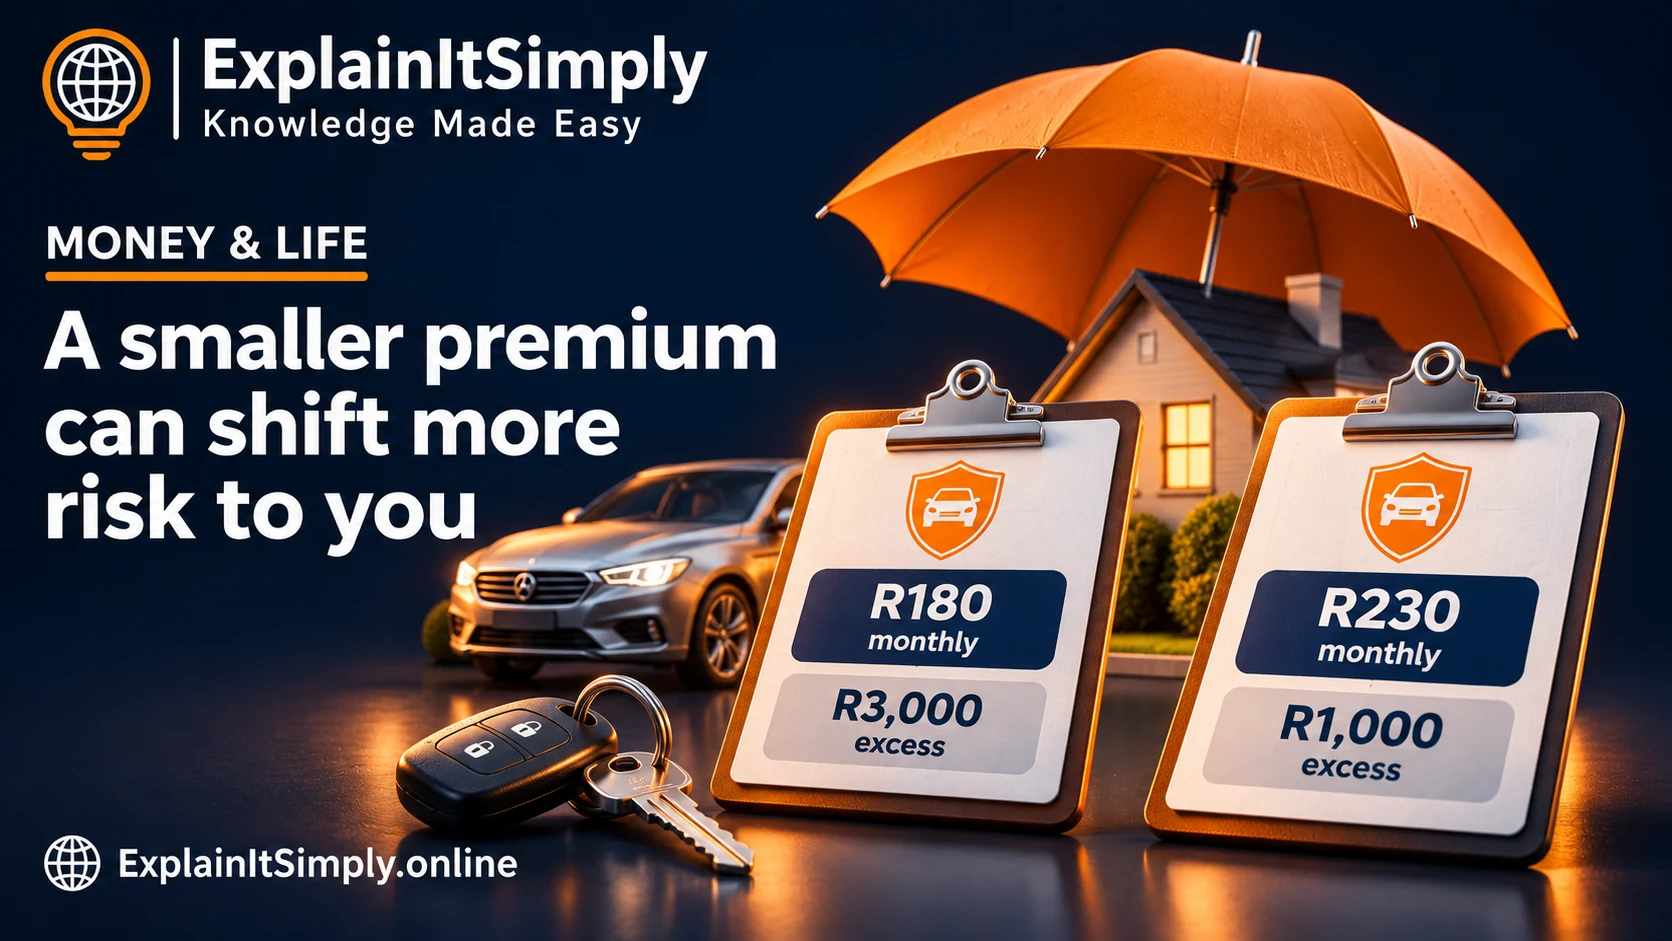
A closer lookA smaller premium can shift more risk to you
Compare two fictional policies covering the same event. One has a R180 monthly premium and R3,000 excess; the other has a R230 premium and R1,000 excess. Over a claim-free year their premiums total R2,160 and R2,760.
Work through the distinction
The R600 annual premium difference does not settle the decision. In this simplified comparison, an accepted claim could leave very different out-of-pocket amounts. Read exclusions, limits and the actual excess wording; coverage may differ even when product names look similar.
Which figure is paid even in a claim-free year?
Choose an answer to see feedback. You can try again.
Show the answer and explanation
The premium. The R600 annual premium difference does not settle the decision. In this simplified comparison, an accepted claim could leave very different out-of-pocket amounts. Read exclusions, limits and the actual excess wording; coverage may differ even when product names look similar.