By Ronnie Mbuqe
Each payment draws little attention while repetition accumulates the cost. The relevant unit is the full period over which the commitment continues.
A fictional R50 weekly payment totals R2,600 over 52 weeks. Converting the unit makes the commitment visible; it does not decide whether the service is worthwhile.
RM
Ronnie Mbuqe
Author · ExplainItSimply
24 July 2026
8 minute read
English
The short version
Simple habits that help people budget, save, avoid debt traps, and feel more in control.
Financial control rarely arrives through one dramatic decision. It grows when ordinary actions, checking where money went, planning irregular expenses, saving on payday and dealing with expensive debt, are repeated often enough to create breathing room. The aim is not a perfect budget. It is having more choices when real life changes the plan.
Everyday finance
Small money habits change the decisions you have available later
Money habits matter because many financial outcomes are repeated decisions instead of one dramatic event. Tracking spending, building a small emergency buffer, paying expensive debt and saving automatically can gradually reduce how often a surprise forces you into another costly choice. The benefit is not perfection. It is creating more room to choose.
Money Habits That Make Life Easier in a real situation
Take a case where two people earn the same amount. One spends every available rand and uses credit whenever a tyre, school cost or medical bill appears. The other automatically moves a modest amount into an emergency account each payday. After several months, the second person may be able to handle the same surprise without borrowing. The habit changed the cost of the emergency even though the salary did not change.
The practical takeaway
Good habits also reduce decision fatigue. An automatic transfer on payday does not depend on remembering to save at the end of a difficult month. A written spending plan makes trade-offs visible before the account balance becomes the only signal.
One misconception to clear up
A budget is not a punishment and it is not proof that someone has too little money. It is simply a plan for where available money needs to go, including enjoyment and goals as well as bills.
Why can an automatic payment be easy to forget but still shape your budget?
Automatic payments reduce effort, but they can also hide continuing commitments.
Trace the explanation
Review recurring amounts and what they provide. A payment's convenience does not remove its opportunity cost.
Source and further reading: Consumer Financial Protection Bureau
A habit becomes powerful when it removes a repeated decision
People often depend on motivation for financial behaviour: “I will save whatever is left at the end of the month.” The problem is that every day creates another chance to spend that money first. An automatic transfer after payday reverses the order. The saving happens by default, and spending adapts to what remains. The amount can be small; the important change is that the decision no longer has to be won again every week.
The same idea applies to bills and debt. Calendar reminders, debit orders and a short monthly review can prevent avoidable late fees. A separate account for annual costs can stop car licences or school expenses from feeling like emergencies. Financial habits are not about perfect discipline; they are about designing a routine that makes the useful action easier to repeat.
Check your grasp of money habits
Try this question using the ideas from this article. Open the explanation after choosing your answer.
Question 1
You want to save monthly but often spend what remains before payday. Which change directly addresses that pattern?
A. Wait and save whatever is left at month-end
Show explanation
This keeps saving dependent on whatever remains after spending.
B. Schedule a realistic transfer soon after payday, while keeping enough for essential bills
Show explanation
Correct. A planned transfer makes saving a deliberate priority; the amount should still be affordable.
C. Set an unrealistic target to force yourself to spend less
Show explanation
A target that cannot be sustained may be abandoned quickly.
Explain it in your own words
Describe one small money habit you could repeat each month and how you would know whether it helps.
Compare with a model answer
Examples include reviewing subscriptions, recording spending weekly, setting aside money for annual bills or making an affordable scheduled savings transfer. A simple monthly comparison can show whether it helps.
Common questions on money habits
Why do habits work better than willpower for managing money?
A habit removes the need to decide fresh each time, while willpower runs out, automatic systems are easier to sustain for months at a time.
What makes a money habit sustainable?
One you can repeat for a year without much effort, not one that looks impressive for a few days and then stops.
Where should I start if I want to build better habits?
Pick one small, specific action, like an automatic transfer to savings, and let it run before adding another.
How much should I save?
There is no universal percentage that fits every household. Start with an amount you can repeat, then increase it as debt falls or income improves.
Why build an emergency fund before investing heavily?
Investments can fall in value or be difficult to access at the wrong moment. Emergency cash is designed for short-notice costs so long-term investments can stay invested.
What is lifestyle inflation?
It is the tendency for spending to rise as income rises, which can leave saving unchanged even after a pay increase.
Are small purchases the main reason people struggle?
Not always. Housing, transport, debt and income usually matter far more. Small habits help, but they should not distract from the large fixed costs in a budget.
Why should a money habit include a trigger rather than only a goal?
A broad intention leaves the next action undefined. A specific routine links an action to an event you can recognise.
For example, review upcoming bills when income arrives, using the actual payment dates. The purpose is to make a decision repeatable rather than rely on remembering it at the right moment.
Practical points to remember
Key takeaways
- Track where money goes each month.
- Pay important needs before wants.
- Save something, even if it is small.
- Avoid borrowing for things that disappear quickly.
- Review spending regularly instead of waiting for a crisis.
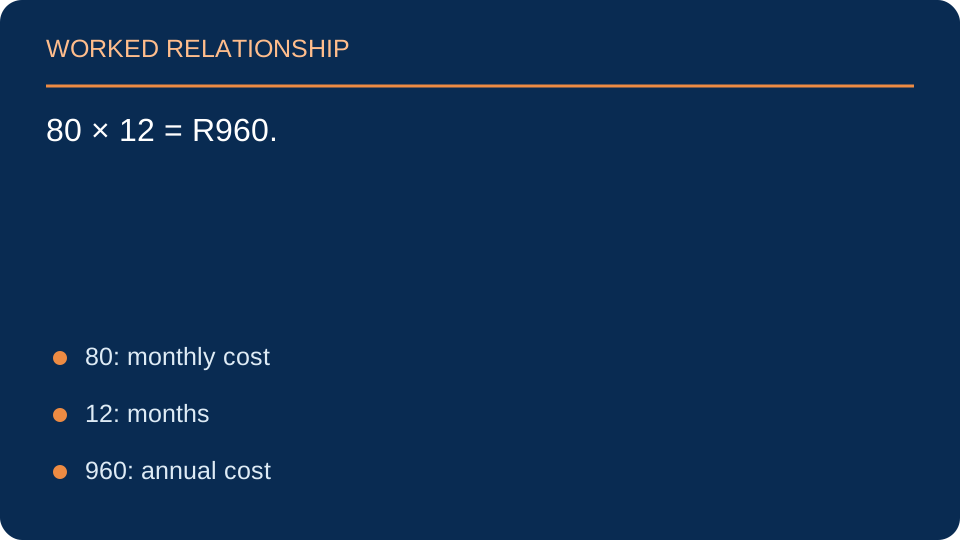
A fictional subscription costs R80 monthly. How much does it cost over 12 months if the price stays unchanged?
Trace the explanation
80 × 12 = R960. Use the annual total to compare it with its value and alternatives, while remembering when the payments fall due.
Source and further reading: Consumer Financial Protection Bureau
A habit is easier to adjust when you can see its trigger
Instead of recording only 'spent R80', note what prompted the purchase: hunger after work, an app notification or a recurring social plan. The same total can have different causes, and each cause suggests a different practical change.
Try a one-week observation without inventing a perfect future budget. Mark repeat purchases, distinguish needs from optional choices and estimate one realistic change. A habit that saves R50 cannot repair a R3,000 shortfall alone, but measuring it prevents both exaggeration and guesswork.
Notice the trigger to Test one realistic adjustment
Does one unplanned purchase erase every useful habit?
No. Review the pattern and the size of its effect. A practical plan needs a way to recover from ordinary variation rather than treating one event as total failure.
Small decisions become a money system
A money habit is powerful because it repeats without needing a fresh decision every day. Automatically moving a fixed amount to savings after payday, checking subscriptions once a month and waiting before an unplanned purchase are simple examples. None is dramatic, but together they change what remains at the end of the month.
Small Systems Beat Occasional Motivation
A money habit works best when it does not depend on remembering at the end of every month. If saving happens only after spending, there may be nothing left to save. An automatic transfer shortly after payday reverses the order: the saving decision is made first and the remaining balance becomes the amount available for other choices.
The same idea applies to irregular expenses. Vehicle licences, school costs, annual subscriptions and festive-season spending may feel like surprises, but many arrive on a predictable schedule. Setting aside a small amount each month turns a large future bill into a series of manageable contributions.
Tracking also needs to be simple enough to continue. You do not need a complicated spreadsheet if three categories, committed costs, flexible spending and future goals, already reveal where the problem is. A useful system is one you can repeat for twelve months, not one that looks impressive for three days.
You discover three services you rarely use. What would you check before cancelling them?
One reasoned response
Check usage, cancellation terms, linked benefits and whether any service is essential. Make a deliberate decision from actual records rather than cancelling only the most recently noticed charge.
Source and further reading: Consumer Financial Protection Bureau
Further reading
This article is educational and not personal financial advice. Money rules, rates and consumer protections can change, so check current information with South African authorities.
Sources
Sources and further reading
A closer lookCheck the statement against the story
Three R35 snacks each week cost R105. Over four weeks that is R420, rather than a vague estimate of about R100 a month. This is a four-week example, not an exact conversion for every calendar month.
Work through the distinction
Small repeated purchases become visible when the frequency is recorded. Keep the comparison proportionate: if the shortfall is R3,000, eliminating R420 of spending cannot close it alone. Look at major commitments as well.
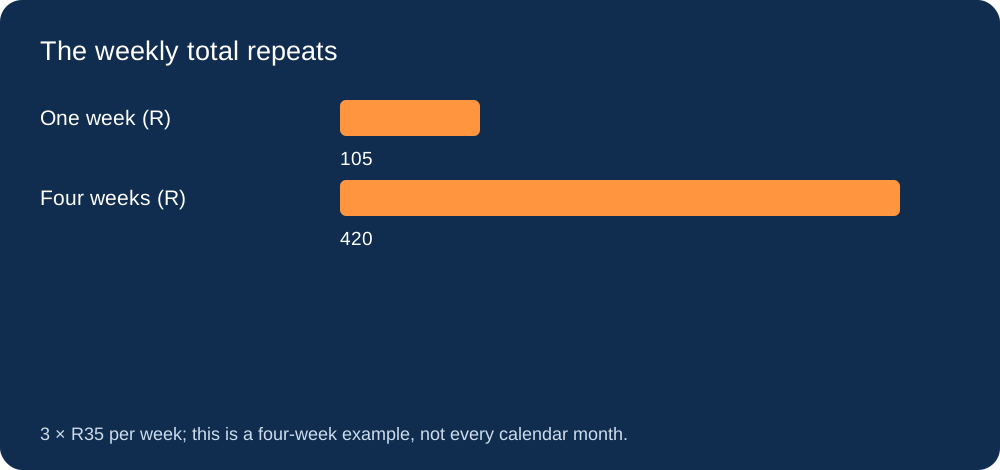
What do the snacks cost over four weeks?
Choose an answer to see feedback. You can try again.
Show the answer and explanation
R420. Small repeated purchases become visible when the frequency is recorded. Keep the comparison proportionate: if the shortfall is R3,000, eliminating R420 of spending cannot close it alone. Look at major commitments as well.